Dow S&P 500 Today: Stocks Rise as Treasury Yields Sink
Dow S&P 500 today: both indexes rose while the Nasdaq trimmed losses as falling Treasury yields steadied Wall Street after hot CPI data.
by Trends DeskOctober 16, 20263 min read
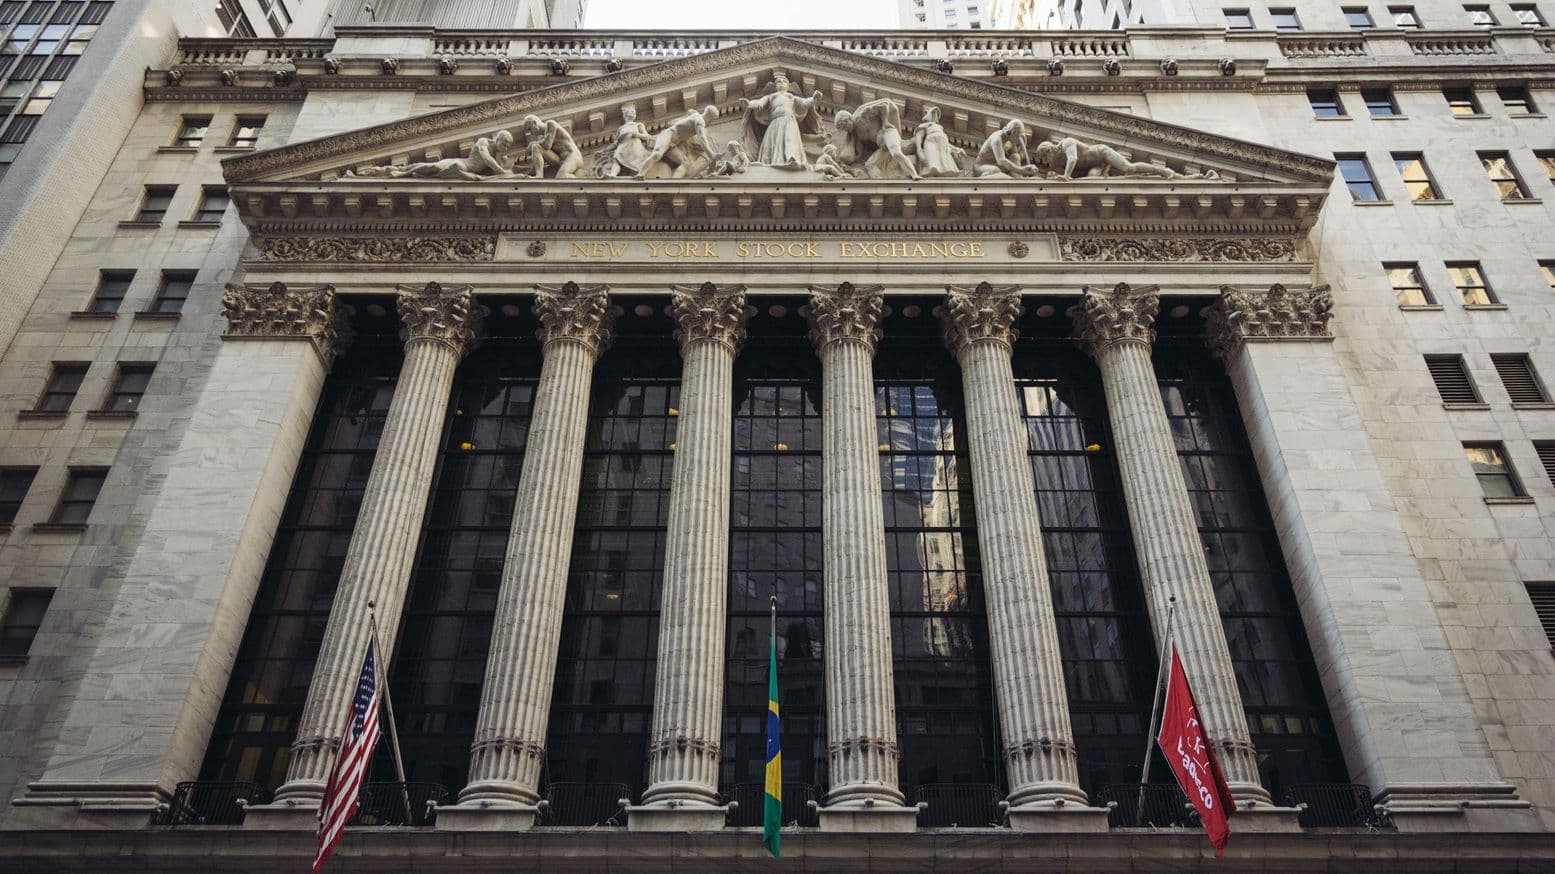
The Dow Jones and S&P 500 both moved higher in the stock market today while the Nasdaq trimmed its losses, as sinking Treasury yields steadied Wall Street a day after the hot inflation CPI data triggered a sharp technology selloff.
The rebound followed a bruising Wednesday session. September consumer prices accelerated to 3.7% annually, up from 3.4%, sending the Nasdaq down 1.9%, its biggest one-day drop since July 23, while the S&P 500 fell 1.11% to 7,718.94, its worst day since July 29.
Chip stocks bore the brunt of the selling. The Philadelphia Semiconductor Index plunged 4.3% for a sixth straight decline as investors dumped AI infrastructure names sensitive to borrowing costs, including Oracle, CoreWeave, AMD and Dell. The rout marked the latest sign of a market struggling with high inflation at a time when AI-fueled corporate borrowing has helped push up global interest rates.
Stock market today: yields sink after CPI shock
Thursday brought relief in the bond market. The 10-year Treasury yield fell about 11 basis points to 5.08% in morning trading, retreating from the 24-year high of 5.34% touched earlier as investors rotated out of equities and into the safety of government bonds.
That rotation is the classic pattern behind moves in the stock market today. When yields fall, the discount rate applied to future corporate earnings drops, easing pressure on stock valuations, particularly for growth and technology shares that sold off hardest on Wednesday.
Oil prices also pulled back in the morning session, though Brent crude remained near $104 on continued attacks on shipping in the Strait of Hormuz. Gold held near $4,143 as investors kept one foot in safe-haven assets.
What could move the Dow Jones next
Traders now turn to Thursday's data deluge: September producer prices, retail sales and weekly jobless claims are all due. A soft round of numbers would reinforce the bond rally, while another hot print could send Treasury yields and rate-hike bets right back up.
Federal Reserve expectations remain the market's central obsession. CME FedWatch priced a 37% chance of an October rate hike after the inflation CPI report, and policymakers meet Oct. 27-28 with inflation running well above their 2% target.
Analysts say the tug-of-war between the inflation CPI data and Fed policy will likely dominate trading until the central bank meeting, leaving little room for complacency on either side of the market.
Stocks in a volatile quarter
The choppy action underscores how fragile the fourth-quarter rally has become, with the Dow Jones caught between resilient corporate earnings and a bond market warning that higher-for-longer interest rates may be back. Analysts expect 30.6% third-quarter earnings growth for the benchmark index, a bright spot amid the gloom.
For investors watching Wall Street, the message is familiar: inflation data is driving everything. Until price pressures convincingly cool, every trading session is likely to hinge on the next number out of Washington.
With the Fed meeting less than two weeks away, markets are bracing for more swings before policymakers show their hand on interest rates.