Mortgage Payment Now Eats 40% of After-Tax Income
The typical monthly mortgage payment on the ~$435,000 median US home will reach 40% of average after-tax income in October, up from 35% in January.
by Trends DeskOctober 21, 20262 min read
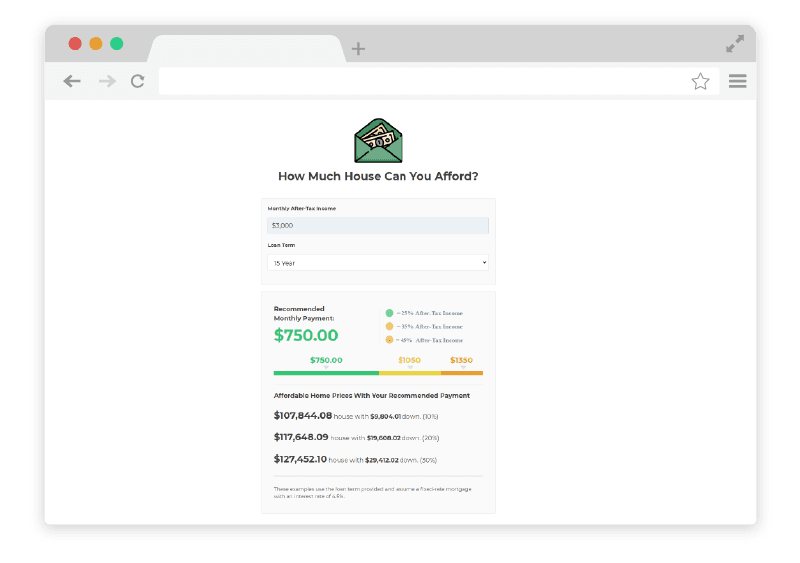
In October the typical mortgage payment on a median-priced American home will take 40% of the average household's after-tax income, up from 35% in January, according to Pantheon Macroeconomics data reported by ABC News.
Higher mortgage rates are the cause. With the average 30-year fixed rate above 7%, the monthly payment on the roughly $435,000 median home is hundreds of dollars higher than at the start of the year.
The move from 6% to 7% hurt the most. Pantheon found that the one-point rise priced roughly 6 million more Americans out of affording the median home. Five percentage points of income in nine months is an unusually fast climb, and it came almost entirely from rates, not prices. Even January's 35% was already above traditional comfort levels.
Why the burden keeps growing
Home prices haven't fallen to offset higher rates. Most homeowners are locked into cheap pandemic-era loans, so listings are scarce and sellers have little reason to cut prices. Buyers take the full hit.
Other costs are rising too: insurance premiums, property taxes and maintenance. But the housing payment is still the biggest item in most household budgets, and the one most directly tied to Federal Reserve policy.
Pantheon describes the 40% figure as a national average. The real burden depends on local incomes and prices, but it is rising almost everywhere.
What 40% means
Housing economists have long used about 30% of income as a rough affordability line. At 40%, households have much less left for savings, childcare or emergencies, and buyers in lower-cost regions, where incomes trail the national average, get priced out.
Renters hoping to buy face a hard sum. Saving for a down payment while paying high rent is difficult enough. Qualifying for a loan that eats two-fifths of take-home pay is harder.
ABC News noted that the October reading captures the full effect of the autumn rate spike.
Will payments come down?
That would take lower mortgage rates, falling prices or faster income growth. None looks close, and borrowing costs show little sign of easing. A real drop in rates would bring the payment share down quickly; steady wage growth would do it more slowly.
Until then, the monthly payment, more than the sticker price, decides who can afford to own a home.