US retail rents slow to weakest pace since 2017
US retail rents grew 1.6% in the third quarter of 2026, the weakest annual pace since 2017, according to CoStar Group data published October 26.
by Trends DeskOctober 27, 20264 min read
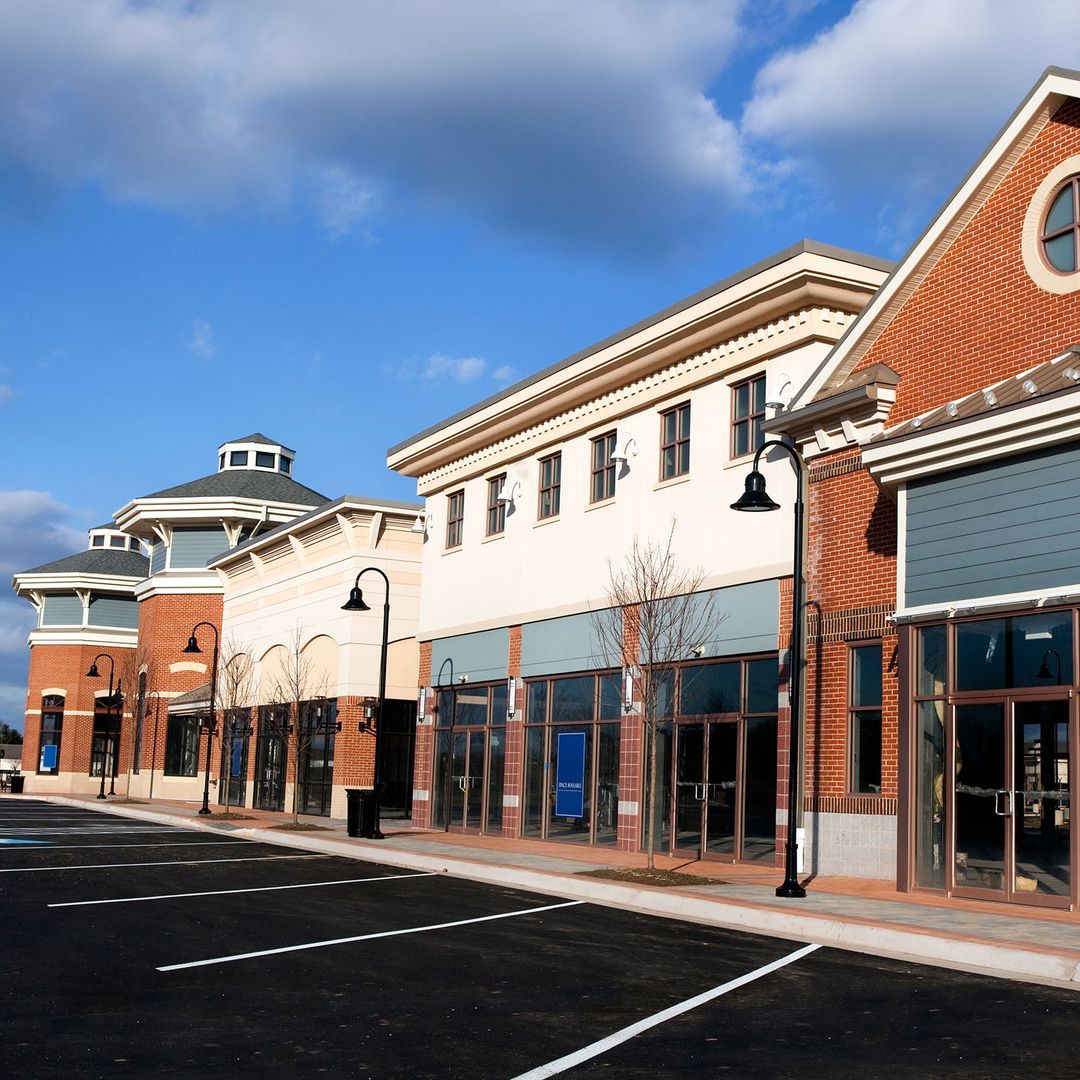
US retail rents grew at their slowest annual pace since 2017 in the third quarter of 2026, even as tenant demand held up for a second straight quarter. CoStar reported annual asking rent growth of 1.6 percent, down from 2.3 percent in the second quarter and 2.9 percent a year earlier. US retail rents are now rising more slowly because retailers are less able to absorb higher occupancy costs, and landlords have less room to raise advertised rates. The October 26 report said the slowdown points to limits on pricing power, rather than a collapse in demand for shop space.
Advertised rents are the rates listed across the market, rather than the rent agreed in any single lease. That distinction matters when landlords report larger increases on newly signed or renewed leases. Those leasing spreads compare a new rent with the rent previously paid for the same space, so a landlord can report a strong spread while asking rent growth across the wider market slows. CoStar based its findings on its own property market data, which has not been independently reproduced from property level records.
Slower across formats
US retail rents slowed in every major property category compared with a year earlier. Power centers and neighborhood shopping centers recorded about 2.4 percent annual growth, while strip centers and malls were near 1.7 percent. General retail properties, the largest segment by inventory, recorded about 1.0 percent growth. Brandon Svec, the firm's national director of retail analytics, linked the slowdown in part to elevated operating expenses and greater selectivity by retailers about expansion. Tenants in discretionary categories face particular pressure when sales growth does not keep pace with rising costs.
The pattern held across formats because the same cost pressure applied to different kinds of shop space. Power centers, which group large retailers together, and neighborhood shopping centers, which serve nearby households, still grew faster than the national average, but both were slower than a year earlier. Strip centers and malls sat close to the national pace. General retail, which covers standalone shops and other properties outside centers, grew slowest. For landlords, the result is a narrower gap between asking rents and the rents retailers are willing to pay for new space.
Market by market
US retail rents varied widely among large metropolitan markets in the third quarter. Among markets with at least 100 million square feet of retail inventory, Cincinnati led with 6.2 percent annual asking rent growth, followed by Nashville at 5.3 percent and Charlotte at 5.0 percent. By contrast, asking rents fell 1.4 percent in Pittsburgh and 1.3 percent in San Diego. Those figures describe asking rents across the broader market, rather than rents negotiated in any particular lease, so individual deals in the same city can look very different.
The spread between the strongest and weakest large markets shows that national figures hide local conditions. Cincinnati, Nashville and Charlotte each grew at more than three times the national rate, while Pittsburgh and San Diego moved in the opposite direction. Retailers weighing new stores must therefore judge each market on its own rents, sales and costs, rather than on a national average. Landlords in weaker markets face a harder task in holding advertised rates when tenants can point to falling rents nearby.
How far rents can go
US retail rents are likely to stay under pressure while occupancy costs weigh on retailers, the findings suggest. A second consecutive quarter of solid tenant demand did not lift US retail rents, which indicates that demand alone is not enough to restore faster rent rises. Retailers must weigh rent against sales, wages, insurance and other operating costs, and many are choosing to expand only where the numbers work. Landlords who push advertised rates too far risk longer vacancies or tenants who choose a smaller space.
Investors reading the report should separate advertised rent growth from leasing spreads, the report said. A strong spread on one renewed lease does not prove that market rents are rising at the same pace. Asking rent growth tracks advertised rates across the market, while a spread tracks one lease against its prior rent. With asking rent growth at 1.6 percent, the weakest pace since 2017, landlords have less headroom to raise rates without testing how much cost retailers can still absorb.