Week ahead markets face oil, GDP and Fed tests
Week ahead markets open after US stocks fell Friday as rising oil prices revived inflation concerns, with Q3 GDP and the Fed decision due in the week ahead.
by Trends DeskOctober 25, 20263 min read
Week ahead markets open after US stocks fell into Friday close, ending a volatile week lower as rising oil prices revived inflation concerns ahead of the October 28 Federal Reserve decision. Reuters reported that US stocks ended Friday lower while technology shares steadied, and selective semiconductor buying helped the Nasdaq hold up better than the broader market without overcoming the risk averse tone.
The closing levels tell the Friday story plainly. The S&P 500 fell 39.75 points, or 0.52 percent, to 7,623.68. The Nasdaq Composite fell 53.52 points, or 0.21 percent, to 25,955.34. The Dow fell 652.82 points, or 1.23 percent, to 52,215.16. The Russell 2000 fell 8.13 points, or 0.29 percent, to 2,775.90, using the AP closing table as cited in the WXYwaves Friday brief.
Oil was the principal pressure point. December Brent settled at 116.72 dollars a barrel, up 3.55 dollars, and December WTI settled at 103.27 dollars, up 3.80 dollars, as supply concerns intensified. Brent crude topped 116 dollars, with later coverage placing oil at a five month high, as renewed Middle East violence threatened global supplies. Reports discussing further US and Israeli strikes on Iran added uncertainty heading into the weekend, although those additional strikes were not confirmed.
Oil prices shape the week ahead markets
Oil prices matter for the week ahead markets because they feed directly into inflation expectations and borrowing costs. When oil rises, transport and energy costs rise with it, and traders start to ask whether inflation will stay higher for longer. That question was central on Friday, when the oil rally put bonds back under pressure after yields had fallen sharply on Thursday amid signs of easing AI related debt supply.
Treasury markets remained unsettled through the session. The US 10 year yield rose 4 basis points to 5.00 percent on Friday, but finished 9 basis points below the previous Friday. Far term Treasuries lost 0.54 percent on Friday. Gold failed to sustain support from lower yields: after initially rebounding around 4,000 dollars, it broke below that level despite the US 10 year yield dropping below 5 percent. Gold fell 0.63 percent, and 3,942 dollars emerged as the next technical support level under pressure, according to the AlphaTraderNews recap.
Q3 GDP, Federal Reserve decision and week ahead markets
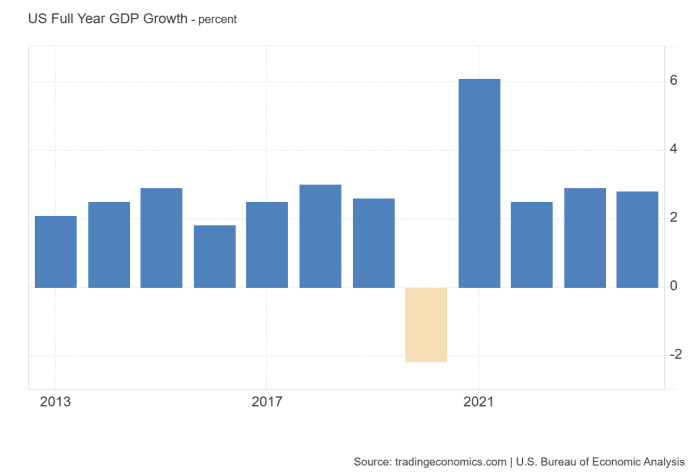
The calendar builds toward two releases. The Federal Reserve decision is due on Wednesday, October 28, at 18:00 GMT. Thursday then brings the advance estimate of Q3 GDP, forecast to accelerate to an annualised 3.2 percent from 2.2 percent, together with September PCE inflation. The headline PCE measure is expected to rise 0.5 percent month on month, its largest increase since March, lifting the annual rate to 3.7 percent from 3.4 percent, according to the Kalkine week ahead summary. Those figures are forecasts, not outcomes.
What traders watch as the week ahead markets open
Monday brings the Chicago Fed activity index and the Dallas Fed manufacturing index, according to the WXYwaves brief. Tuesday brings durable goods and wholesale inventories data in the TalkMarkets forecast, alongside consumer confidence forecast at 83.5 against a prior 81.9. Friday Employment Cost Index, forecast to ease to 0.8 percent from 0.9 percent, then offers a final read on wage pressure, Kalkine reported.
Developments in the Middle East remain the backdrop variable most capable of moving inflation expectations, Kalkine noted, where disruption to oil supply continues to drive energy costs higher. The US midterm elections on November 3 loom just beyond the week horizon. For now, the week ahead markets face a sequence for week ahead markets watchers that runs from oil driven Friday losses through a central bank decision and growth and inflation data, with earnings reports landing in between. Each release in the week ahead markets will be read against forecasts that are already set, and against a Friday close that left stocks lower and oil higher.