Sitharaman chairs 30th FSDC meeting on financial stability
The Finance Minister chaired the 30th FSDC meeting in New Delhi, where regulators flagged the AI boom and rising bond yields as risks.
by Trends DeskOctober 24, 20263 min read
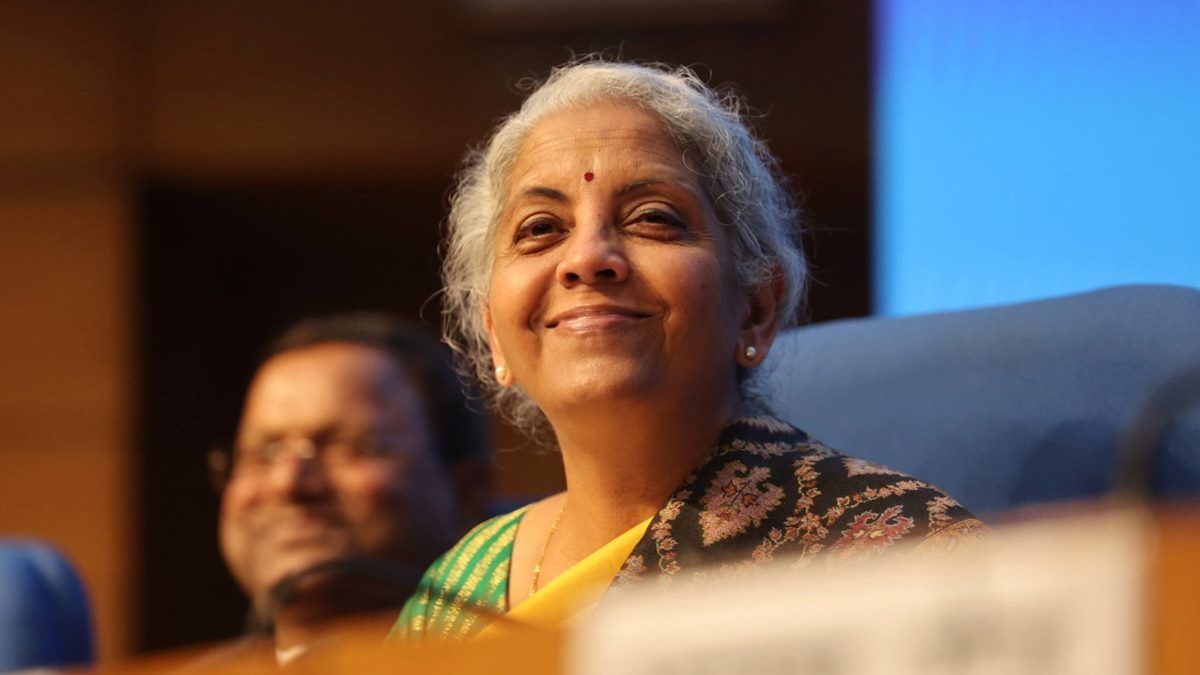
Union Finance Minister Nirmala Sitharaman on Friday chaired the 30th meeting of the Financial Stability and Development Council (FSDC) in New Delhi, bringing together the Reserve Bank of India (RBI) Governor, the heads of financial sector regulators and senior government officials. The FSDC meeting put the spotlight on risks from geopolitical uncertainty, the artificial intelligence (AI) boom and a steep rise in global bond yields.
The FSDC meeting was attended by the secretaries of the Department of Economic Affairs, the Department of Revenue and the Department of Financial Services, along with the Chief Economic Adviser to the government. The chairpersons of the Securities and Exchange Board of India (SEBI), the Insurance Regulatory and Development Authority of India (IRDAI), the International Financial Services Centres Authority (IFSCA), the Pension Fund Regulatory and Development Authority (PFRDA) and the Insolvency and Bankruptcy Board of India (IBBI) were also present. Senior officials from the Ministry of Electronics and Information Technology (MeitY) and the Indian Computer Emergency Response Team (CERT-In) took part as well.
According to a finance ministry statement, the council took note of emerging trends in the domestic and global macro-financial situation. It stressed the need to stay alert in view of ongoing geopolitical uncertainties, the AI boom and the sharp rise in global bond yields. The council said proactive efforts were needed to reduce potential risks to financial stability while putting adequate safeguards in place for the resilience of the financial system. Members also decided to strengthen coordination between regulators for the wider development of the financial sector.
What the FSDC meeting covered
The FSDC meeting discussed measures to promote financial technology innovation, including exploring the prospects of tokenisation of financial assets and other real-world assets. Nirmala Sitharaman also urged the council to meet more frequently, on a predefined schedule, citing rising geopolitical headwinds and global uncertainty.
The FSDC meeting reviewed strategies to implement pending decisions and Budget announcements aimed at strengthening the domestic investment ecosystem. That work includes improving resource flows to investment, including through the GIFT International Financial Services Centre (GIFT-IFSC), and reducing the cost of financial intermediation.
Cyber resilience of the Indian financial sector was also on the agenda. The FSDC meeting took note of the Financial Sector Cyber Security Strategy prepared by an inter-ministerial group of financial regulators and cybersecurity agencies, working with the Department of Economic Affairs, the Department of Financial Services and MeitY. Discussions covered India's preparedness to protect critical information infrastructure, the resilience of protection systems and cybersecurity preparedness among regional rural banks.
Why the FSDC meeting matters
The FSDC is the government's highest-level forum for issues of financial stability, financial sector development and coordination among regulators. Its mandate also covers financial inclusion, financial literacy and macro-prudential supervision, including monitoring risks from large financial conglomerates. The council was set up through a government notification dated December 30, 2010, and is chaired by the Union Finance Minister, with the RBI Governor, senior Finance Ministry officials and the heads of major financial sector regulators as members.
Friday's FSDC meeting was the 30th since the council was formed. The call for more frequent meetings, and the focus on the AI boom and bond yields, shows regulators are tracking how fast-moving global forces can reach India's financial system. The council's emphasis on vigilance and coordination points to a closer watch on emerging risks in the months ahead, with the finance ministry saying members agreed on the need to strengthen the resilience of the financial system.